Vantage Asset & Commercial Finance

Commercial Mortgages & Buy-to-Let
Commercial mortgages and buy-to-let finance
Finance for the property behind your business
Whether you are buying your own premises, adding to a rental portfolio or refinancing a building you already own, we help you find a commercial or buy-to-let mortgage that fits your plans and your numbers.
At a glance
- Who it is for
- Business owners, property investors and landlords
- Typical deposit
- Usually around 25% to 40%, depending on the property and lender
- Loan terms
- Often up to 25 years
- Borrowing as
- An individual, partnership or limited company
Property finance, explained simply
Buying, refinancing or investing in property

A commercial mortgage is a loan secured against a property used for business, such as a shop, office, warehouse or mixed-use building. A buy-to-let mortgage is secured against residential property you rent out, whether that is a single flat or a growing portfolio.
Lenders look at these very differently from a home mortgage. They want to understand the property, the income it produces or the strength of your business, and your experience. That is where we come in: we take the time to understand your plans, prepare your case properly and approach the lenders most likely to say yes.
What we arrange
Mortgages for every kind of property plan
Every lender has its own appetite for different properties and borrowers. We match your plans to the lenders that suit them.
Owner-occupier commercial mortgages
Buy the premises your business trades from, such as a shop, office, workshop or surgery, instead of paying rent to someone else.
Commercial investment mortgages
Finance for let commercial property, where lenders focus on the rental income, the tenant and the length of the lease.
Semi-commercial and mixed-use
Buildings with a commercial unit and residential space, such as a shop with flats above.
Buy-to-let and portfolio mortgages
Mortgages for landlords, including limited company buy-to-let, HMOs, holiday lets and portfolio refinancing.
Refinancing and capital raising
Move to a better deal when a term ends, or release equity from property you own to fund your next step.
Specialist property
Premises that need a specialist lender, such as care homes, hotels, pubs, restaurants and healthcare buildings.
Property types
The properties we can help you finance
If your property is not listed here, get in touch anyway. There is often a lender for it, and we will tell you honestly if there is not.
- Shops and retail units
- Offices
- Industrial units and warehouses
- Mixed-use buildings
- Restaurants, cafes and pubs
- Healthcare and dental premises
- Blocks of flats
- Houses in multiple occupation (HMOs)
- Holiday lets
- Rental portfolios
Before you apply
What lenders look at
We review all of this with you before approaching any lender, so there are no surprises later.
01
Your deposit
Most lenders ask for a deposit of around 25% to 40%. The stronger your position, the more options you usually have.
02
Income and affordability
For your own premises, lenders review your business accounts. For investment property, they look at the rent it produces.
03
The property
Its type, condition, location and how easily it could be sold or re-let all affect which lenders will consider it.
04
Your experience
Your credit history and track record as a business owner or landlord help lenders get comfortable with your application.
How it works
A clear route from first call to completion
1
Initial conversation
We talk through the property, your plans, your timescales and your circumstances.
2
Options and agreement in principle
We research suitable lenders, explain your options clearly and aim to secure an agreement in principle.
3
Application and valuation
We package your application, liaise with the lender and help arrange the valuation.
4
Offer and completion
We keep you updated through the legal work until the funds are released.
Commercial mortgages usually take around 8 to 12 weeks from application to completion, and sometimes longer for more complex cases. Buy-to-let can often be quicker.
Helpful to have ready
- Two to three years of business accounts or tax returns (SA302s)
- Recent business and personal bank statements
- Details of the property, including any leases or tenancy agreements
- Photo ID and proof of address
- A summary of your assets and liabilities
- A short business plan if the business is new
Do not worry if you do not have everything yet. We will tell you exactly what your lender needs.
Why Vantage
Personal advice from people who know property finance
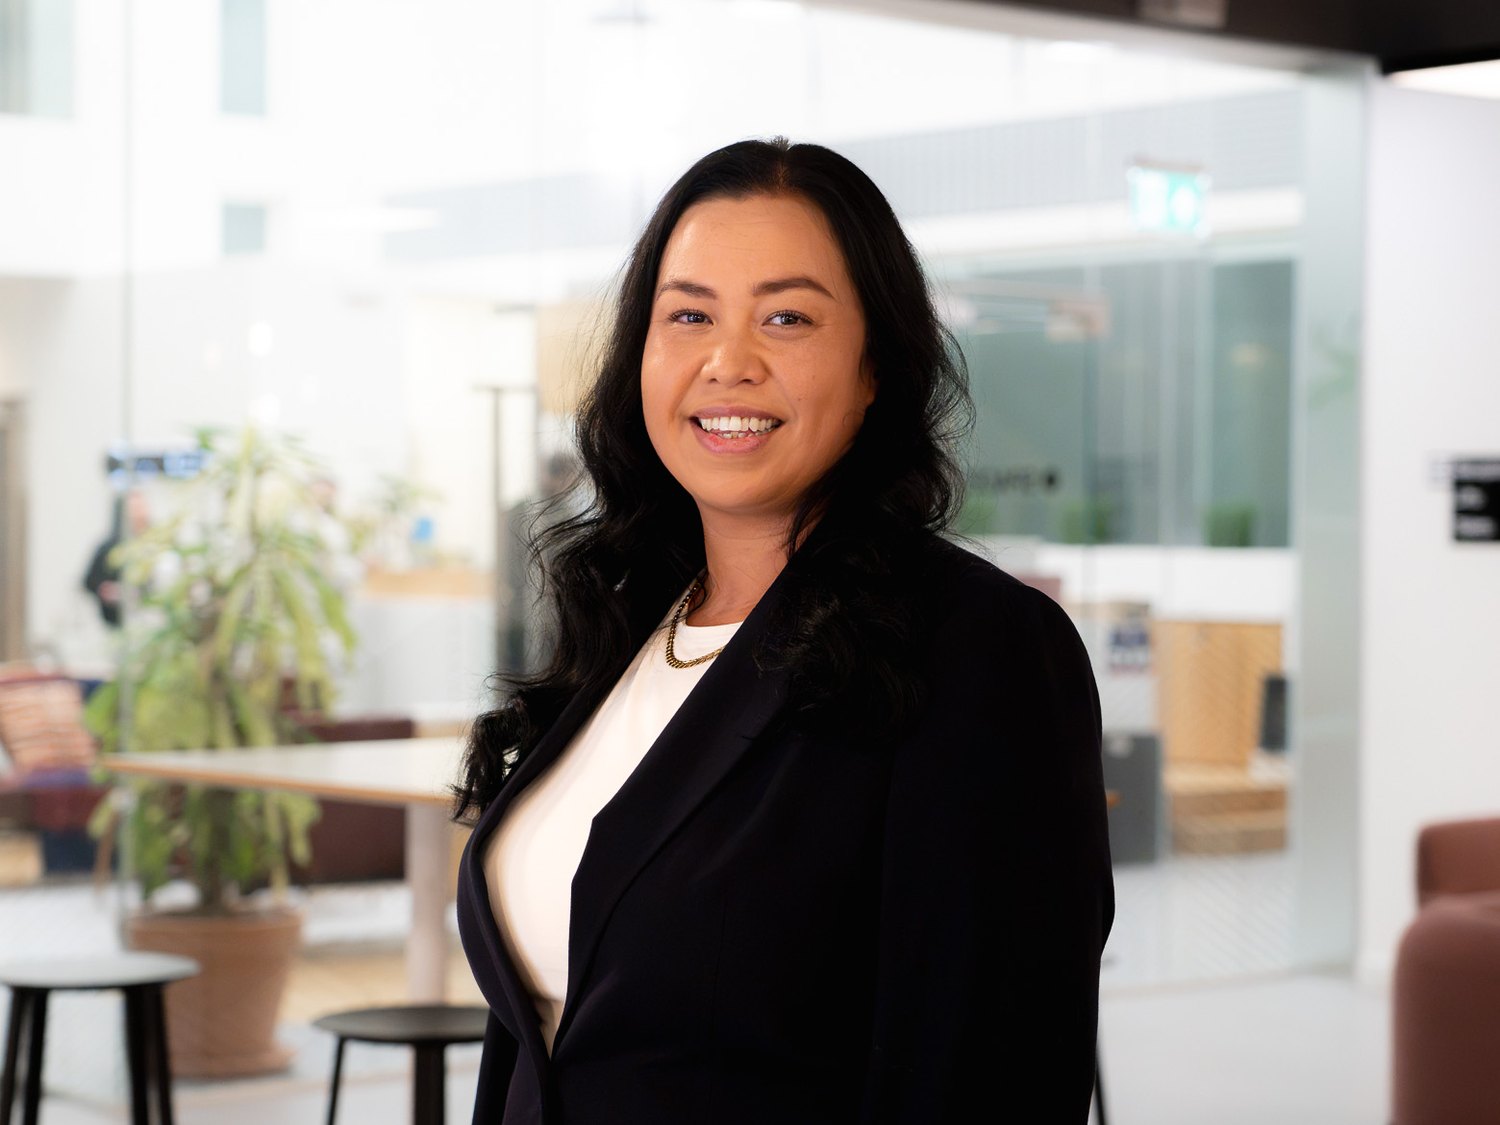
Vantage is run by husband and wife team Charles and Melanie. Charles has spent nearly 20 years helping people with their mortgages, and together they bring that experience to business owners, landlords and investors.
You deal with us directly from the first conversation to completion, and we can draw on specialist support and a wide range of lenders when your case needs it.
FAQs
Common questions
Can’t see your question? Send us a message and we will be happy to help.
We arrange commercial mortgages and buy-to-let finance for businesses across Hampshire, including Fareham, Portsmouth and Southampton.
What is the difference between a commercial mortgage and a buy-to-let mortgage?
A commercial mortgage is secured against property used for business, such as shops, offices or industrial units. A buy-to-let mortgage is secured against residential property that you rent to tenants. Mixed-use buildings sit in between and are often financed with a semi-commercial mortgage.
How much deposit do I need?
Most lenders look for a deposit of around 25% to 40% for commercial property, and usually around 25% for buy-to-let. The exact amount depends on the property, your experience and your financial position.
Can I borrow through a limited company?
Yes. Many clients buy commercial and buy-to-let property through a limited company, including special purpose vehicles set up to hold property. Lenders will usually ask for personal guarantees from the directors.
Can I get a commercial mortgage for my own business premises?
Yes. Owner-occupier commercial mortgages let you buy the premises your business trades from. Lenders will review your business accounts to check the loan is affordable.
My bank has said no. Can you still help?
Often, yes. High street banks are only one part of the market, and many specialist lenders consider cases that banks decline. We will look at why the application was turned down and whether another lender is a better fit.
How long does a commercial mortgage take?
Usually around 8 to 12 weeks from application to completion, depending on the lender, the valuation and the legal work. Buy-to-let mortgages can often complete more quickly.
Get in touch
Let's talk about your plans
Tell us a little about what you would like to fund and Charles or Melanie will come back to you to talk it through.
Helpful to have ready
- A short outline of what you want to fund
- The approximate amount and timescale
- Property, asset or business details if you have them
Send us an enquiry
We will only use your details to respond to your enquiry. Please read our privacy notice before you send us your information.
Calculators and guides
- Commercial mortgage calculatorMonthly payment, LTV and rental cover
- Commercial mortgages explainedA plain-English guide
- Semi-commercial mortgagesShops with flats above
- Bridging loan calculatorGross loan, interest and redemption
- Development finance calculatorProfit, loan to cost and loan to GDV
- Business loan calculatorMonthly payment and total cost